What is a bordereau in insurance?
The insurance industry is built on the precise exchange of information. At the heart of this data flow lies a foundational, yet often misunderstood, document: the bordereau. In its simplest form, a bordereau is a detailed, itemised report of insurance transactions. It serves as a vital communication tool between different parties in the insurance value chain, providing a summary of business conducted over a specific period (IRMI).
Historically, the term is most associated with reinsurance, where a primary insurer reports to its reinsurer on the risks ceded and claims paid (Investopedia). However, in the modern insurance landscape, the bordereau has become even more critical in the context of delegated authority. Here, intermediaries like a Managing General Agent (MGA) or a coverholder report back to the capacity-providing insurer on the policies they have underwritten and the claims they have managed (Founder Shield).
This dual context is not merely a technical distinction; it reflects a fundamental shift in how insurance is distributed. The rise of the delegated authority model as a major channel for innovation and market access has placed the MGA-to-insurer bordereau at the centre of today's operational and regulatory challenges (The Insurance Network). This report provides an exhaustive guide to the bordereau, exploring its origins, types, and the profound challenges it presents in an era of accelerating digital transformation.
The Origins and Terminology of the Bordereau
From French Margins to Insurance Ledgers
The word "bordereau" has its roots in the French language, deriving from the Middle French "bordrel" and the Old French "bort," which both mean border, edge, or margin (Merriam-Webster). This etymology points to its original function as a detailed note or memorandum, often written in the margins of a main ledger (Dictionary.com). First appearing in English usage in the late 19th century, the term was adopted by the insurance industry to describe these summary lists (Oxford English Dictionary).
The bordereau is a direct descendant of the manual ledgers that have been the bedrock of commerce and insurance for centuries. From the earliest forms of risk sharing among Babylonian traders to the formalisation of maritime insurance in Edward Lloyd's London coffee house in the 17th century, the need to meticulously record and report transactions has been paramount (Wikipedia). The bordereau represents the institutionalisation of this reporting practice within the complex, multi-layered structure of the modern insurance market.
Bordereau, Bordereaux, and BDX: A Note on Terminology
Navigating the language of insurance requires an understanding of its specific terminology. The word "bordereau" is the singular form, referring to a single report. When discussing multiple reports, the correct plural is "bordereaux," which retains its French form (Collins Dictionary). This persistence of a foreign plural is a small but telling indicator of the insurance sector's deep-rooted traditions and legacy-bound nature.
In modern communication, the perceived cumbersomeness of "bordereaux" has led to the adoption of a common industry shorthand: BDX. This abbreviation is frequently used in emails, internal documents, and even in the naming of technology solutions designed to manage these reports (LMA). The use of this modern acronym for an old-world term neatly encapsulates the central theme of this report: an archaic process striving for relevance in a fast-paced, digital environment.
The Bordereau's Role in the Insurance Value Chain
The Traditional Context: Reporting to Reinsurers
The classic application of the bordereau is within the reinsurance sector. In this relationship, a primary insurance company, known as the ceding company, transfers a portion of its risk portfolio to a reinsurer. To facilitate this, the ceding company periodically provides the reinsurer with bordereaux detailing the specifics of the transferred risk (Investopedia).
These reports serve a crucial accounting and risk management function. A premium bordereau informs the reinsurer of the specific policies it is now covering, allowing it to book the corresponding premium revenue and understand its potential liabilities. Conversely, a loss bordereau details the claims that have been paid against those policies, for which the reinsurer is now partly responsible. This information is essential for the reinsurer to manage its capital and assess its overall exposure.
The Modern Imperative: Delegated Authority and the MGA-Insurer Relationship
While the reinsurance context is important, the most prevalent use of the bordereau today is within the delegated authority framework. Delegated authority is a model where an insurer grants a third party, such as an MGA or a coverholder, the authority to perform functions on its behalf. These functions most commonly include underwriting new policies and handling claims management (Moore UK).
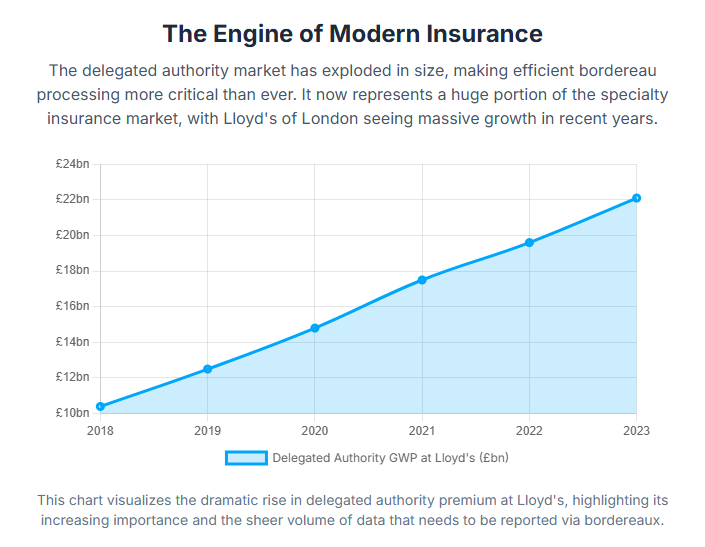
This model has become a cornerstone of the UK and global insurance markets, enabling insurers to access specialist expertise and enter niche markets with greater agility. The scale is significant; delegated authority business now accounts for over 40% of Lloyd's of London's total premium, having more than doubled to £22.1 billion in 2023 (The Insurance Network).
In this model, the bordereau is the primary mechanism through which the MGA reports its activities to the insurer providing the capital. The "binder agreement," the contract that outlines the delegated authority, stipulates the frequency and format of this insurance reporting (Insurance Training Center). The bordereaux provide the insurer with the only comprehensive view of the risks being written and the claims being paid in its name.
This flow of information carries immense regulatory weight. The Financial Conduct Authority (FCA) makes it unequivocally clear that an insurer cannot delegate its regulatory responsibility (Addleshaw Goddard). The principal firm, the insurer, remains fully accountable for the actions of its delegated agent and for ensuring that customers are treated fairly (Regulation Tomorrow). Consequently, any inaccuracy or delay in the bordereau process is a direct failure of the insurer's governance and oversight obligations.
A Comprehensive Guide to Bordereau Types
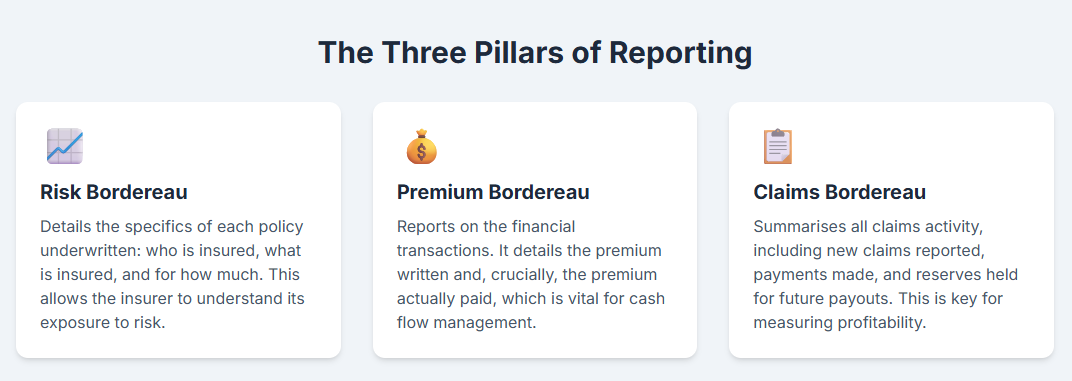
The term "bordereau" is not monolithic; it encompasses several distinct types of reports, each serving a specific purpose. Understanding these different forms is essential for grasping how data flows between partners. The primary categories are premium, risk, and claims bordereaux.
The Premium Bordereau: Tracking Premiums Written and Paid
A premium bordereau is a report that details all premium-related transactions for a given period, which is fundamental for financial accounting. However, it is crucial to distinguish between its two main sub-types, as they provide very different information.
A "written bordereau" lists every policy that has been underwritten and bound within the reporting period, regardless of whether the premium has been collected. This report is vital for the underwriter and the insurer to understand the total gross written premium (GWP) and the full extent of the risk exposure they have taken on (Investopedia).
In contrast, a "paid bordereau" lists only the cash transactions that have actually occurred. This report details the premiums paid by policyholders and received by the MGA. It is the essential document for cash reconciliation, credit control, and managing fund flows from the MGA to the insurer (Synpulse). The distinction is critical; a business might appear healthy on a written bordereau but face serious cash flow issues if the paid bordereau shows significant delays in collection.
The Risk Bordereau: Profiling the Underwritten Portfolio
While a premium bordereau focuses on the financial transactions, a risk bordereau provides granular detail about the nature of the risks themselves. This report lists each policy and describes the specific asset or liability being insured. Its purpose is to give the insurer a transparent view of the portfolio's composition, ensuring the MGA is adhering to the binding authority agreement (The Insurance Data Exchange).
For example, a risk bordereau for a property portfolio includes details like property addresses and sums insured. This allows the insurer to analyse its aggregated exposure to perils like floods and to verify that the MGA has not breached contractual restrictions, such as writing risks in prohibited postcodes or exceeding per-risk limits. In some cases, a combined "Risk and Premium" bordereau is used (Insureon).
The Claims Bordereau: Managing Liabilities and Losses
The claims bordereau is the third critical pillar of insurance reporting. It provides a detailed summary of all claims activity related to the policies written under the delegated authority agreement. This typically includes information on new claims reported, payments made, and the estimated reserves held for outstanding claims (Insureon).
This report is indispensable for effective claims management and financial planning. It allows the insurer to monitor its delegated claims administrator, track trends, calculate loss ratios, and ensure adequate reserves are maintained (Founder Shield). Without accurate claims bordereaux, an insurer is blind to its business performance. To provide a clearer overview, the table below summarises each primary bordereau type, based on the Lloyd's of London Coverholder Reporting Standards (Lloyd's of London).
| Bordereau Type | Purpose | Common Data Fields |
|---|---|---|
| Risk Bordereau | To provide detailed information on the specific risks underwritten, enabling exposure analysis and ensuring compliance with binder terms. | • Unique Policy Number • Insured Name and Address • Inception and Expiry Dates • Class of Business • Risk Location (Address, Postcode) • Sum Insured / Limit of Indemnity • Description of Risk (e.g., Vehicle Details, Property Type) • Applicable Perils and Coverages |
| Premium Bordereau | To report on financial transactions, distinguishing between business written and cash received for accounting and credit control. | • Unique Policy Number • Transaction Type (New Business, Renewal, Endorsement) • Gross Written Premium (GWP) • Insurance Premium Tax (IPT) and other taxes • Brokerage / Commission Amount • Net Premium Due to Insurer • Transaction Currency • Payment Date (for paid bordereau) |
| Claims Bordereau | To provide a summary of all claims activity, enabling loss ratio analysis, reserve management, and oversight of claims handling. | • Unique Claim Number • Associated Policy Number • Date of Loss • Date Claim Reported • Name of Claimant • Peril / Cause of Loss • Amount Paid to Date • Outstanding Reserve Amount • Claim Status (e.g., Open, Closed) |
The Operational Reality: Challenges in Bordereau Processing
Despite its central role, the traditional bordereau process is fraught with operational challenges that create inefficiency, risk, and significant cost. These problems stem largely from its reliance on manual processes and outdated technology, turning what should be a straightforward data exchange into a complex and burdensome task.
The Data Quality Quagmire
The most significant challenge in bordereau processing is data quality. Bordereaux are typically exchanged as spreadsheets, with no enforced standardisation of format or terminology between partners. An insurer may receive dozens of bordereaux from its various MGAs, each with different layouts and data labels. This lack of uniformity creates a "Herculean effort" in data management (Finitas).
Staff must manually cleanse, validate, and map the data from each incoming bordereau into the insurer's own systems. This process is not only incredibly time-consuming but also highly susceptible to human error (PwC). Incomplete or inaccurate data is common, leading to a lengthy and frustrating cycle of queries and corrections between the insurer and the MGA (Synpulse).
The High Cost of Inefficiency
The financial impact of this manual inefficiency is staggering. Manual processes are a major driver of operational costs, and the expense of simply correcting a single data error can be significant, escalating dramatically if it leads to incorrect payouts or regulatory issues (McKinsey & Company).
These issues are compounded by the industry's reliance on legacy insurance software. Many insurers operate on outdated core systems, including antiquated policy administration software, that are difficult to maintain. Research has found that a large portion of an insurer's IT budget is often consumed by simply maintaining these legacy platforms, leaving little for innovation (Accenture). These systems were not designed for modern data exchange, creating data silos that exacerbate bordereau challenges.
Binder Management and Regulatory Scrutiny
The consequences of poor bordereau data extend into the critical domains of binder management and regulatory compliance. If the data is unreliable, it is impossible for an insurer to effectively monitor its binder agreements. It cannot accurately track premium, verify commissions, or check for breaches of underwriting authority (PwC).
This failure of oversight has attracted significant regulatory attention. In 2015, the FCA published its Thematic Review TR15/7, a landmark report on delegated authority which found widespread failings, including inadequate due diligence and insufficient oversight of customer outcomes (Financial Conduct Authority). The report served as a stark warning that the regulator holds insurers directly responsible for the conduct of their delegated partners.
Industry bodies like the British Insurance Brokers' Association (BIBA) have also responded, publishing guidance to help brokers understand their responsibilities when entering into agreements with MGAs (Insurance Business UK). The clear message is that the data exchanged via bordereaux is not just for accounting; it is the primary evidence of an insurer's control over its delegated business.
The Future of Insurance Reporting: Beyond the Bordereau
Given the profound inefficiencies associated with the traditional bordereau, its continued prevalence in the digital age demands explanation. The industry's slow pace of change, coupled with the complexity of replacing embedded legacy systems, has allowed this analogue process to persist. However, its days are numbered as modern technology offers a vastly superior alternative.
An Analogue Relic in a Digital World?
It is worth asking why the bordereau, which is often a spreadsheet acting as a digital version of a 150-year-old ledger, still exists today. It stands as one of the insurance industry's most significant legacy hangovers. It is a periodic, batch-based process fundamentally out of sync with the real-time capabilities of the modern world. This process is a relic of an era before interconnected systems, and its persistence is a major barrier to genuine digital progress.
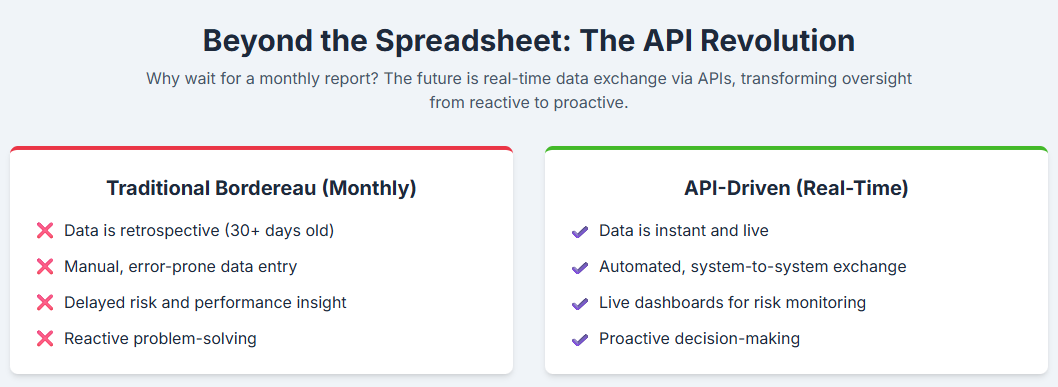
The core problem is that a bordereau is a retrospective snapshot. It tells an insurer what happened last month, or last quarter. In a dynamic market, this time lag is a critical weakness. It prevents proactive risk management and forces insurers into a reactive posture, always looking in the rearview mirror instead of at the road ahead. This is a model that technology has rendered obsolete.
The Case for Real-Time Data: The Power of API Connectivity
The modern alternative to the bordereau is real-time data exchange facilitated by Application Programming Interfaces (API). An API is a set of rules that allows different software applications to communicate with each other directly and instantly. Instead of an MGA compiling and emailing a spreadsheet, an API allows the MGA's policy admin system to send data directly to the insurer's system the moment a policy is bound or a claim is registered (Celent).
This shift requires a commitment to connectivity, interoperability, and an open architecture. An open architecture allows insurers to build flexible ecosystems, integrating best-in-class solutions and data sources seamlessly. This is the technical foundation for moving away from cumbersome, file-based reporting and embracing a more dynamic and efficient model of data exchange.
The Benefits of Modernisation: A New Paradigm for Delegated Authority
The move from periodic bordereaux to real-time API data exchange is more than a technological upgrade; it represents a fundamental shift in the business model of delegated authority. It transforms the relationship between an MGA and an insurer from a periodic reporting arrangement to a continuous, data-driven partnership.
With a live data stream, an insurer's oversight moves from being reactive to proactive. Instead of reviewing last month's bordereau, an underwriter can monitor a live dashboard, receive real-time alerts for any breaches of authority, and analyse portfolio performance as it develops. This enables far superior risk analysis and more effective claims management (Dufrain).
The strategic advantages are immense. This deeper integration fosters a true partnership, enabling collaborative portfolio management and dynamic adjustments to underwriting strategy. It also dramatically increases the speed to market for new product launches, as new products can be configured and deployed rapidly through platforms that use no-code product building tools, all underpinned by clean, accessible, real-time data. This is the essence of a successful digital transformation.
Conclusion: The Enduring Principle of the Bordereau
The bordereau has been an integral part of the insurance industry's plumbing for over a century. It was born from a fundamental need: for partners in a risk-sharing agreement to have a structured and transparent way to exchange data on premiums, risks, and claims. This principle remains as critical today as it was in the 19th century.
However, the physical manifestation of the bordereau, the spreadsheet, is an operational anachronism. Its reliance on manual processes and periodic, batch-based reporting is a profound drag on efficiency, a significant source of operational and regulatory risk, and a formidable barrier to the innovation that the industry desperately needs. In its current form, it is holding the delegated authority market back.
While the spreadsheet is becoming obsolete, the principle it represents is not. The future of insurance reporting lies in honouring the purpose of the bordereau while revolutionising its execution. Modern insurance software platforms, built on an open architecture and API-first principles, are the rightful inheritors of this legacy. They deliver on the promise of the bordereau, providing structured data exchange with a level of speed, accuracy, and insight that was previously unimaginable, paving the way for a more efficient, transparent, and collaborative insurance ecosystem.
Frequently Asked Questions
What is the difference between a bordereau and bordereaux?
A bordereau is a single report: a list of the risks, premiums or claims written under one agreement over a set period, which is usually a calendar month. Bordereaux is the plural. An MGA that sends its insurer a risk report, a premium report and a claims report at the end of each month is sending three bordereaux. The word came into English from French and the insurance market kept the French plural ending, so the form to use in a binding authority agreement, a contract or a job advert is bordereaux, not bordereaus.
In conversation the two words are often swapped, and "bordereaux" has also become the name for the whole job of producing, checking and loading the reports, as in "bordereaux management" or "a bordereaux team". In a contract it pays to be exact, because the agreement names each bordereau a coverholder or MGA must send, the fields it must hold and the day it is due. A missing risk bordereau and a late claims bordereau are two separate breaches of the binding authority, and the insurer will treat them as two separate problems with two separate fixes.
Is it spelt bordereaux, borderaux or bordereau?
Bordereau is the singular and bordereaux is the plural. Both keep the letters "eau" twice: once in the middle of the word and once at the end. Borderaux, without the first "e", is a misspelling, and so are bordreaux, bordereax and bordereuax, all of which turn up in emails, spreadsheet headings and search boxes. Bordeaux is the French city and its wine, which is where many spellcheckers send the word when they do not recognise it.
The spelling matters more than it seems, because systems search for exact text. A column headed "Borderaux Ref" will not match a mapping rule written for "Bordereaux Ref", and a shared folder of files named three different ways is harder to audit than one named the same way every month. Lloyd's, the Lloyd's Market Association and the binding authority wordings used in the London Market all write bordereau and bordereaux, so those are the forms to standardise on in templates, file names and reporting rules. Where a short form is easier, the market writes BDX, which removes the spelling question altogether.
How do you pronounce bordereau, and what does BDX mean?
Bordereau is said "bor-duh-roh", with the stress on the last syllable. Bordereaux sounds exactly the same, because the final x is silent, as it is in French. In speech the only way to tell one from the other is the context: "the claims bordereau is late" means one report, while "the bordereaux are late" means more than one, or the whole reporting process for that month.
BDX is the written shorthand for bordereaux, used in emails, file names, job titles and the names of reporting tools. A "BDX analyst" checks and loads bordereaux for an insurer or a managing agent, and "risk BDX" and "claims BDX" are the two reports most people mean when they use the term. You may also see "bdx" written in lower case in file names such as a month and binder reference followed by "bdx". It means the same thing, and it carries no extra meaning beyond saving the writer from spelling the full word.
What does a bordereau contain, and how often is it sent?
A risk bordereau lists each policy written in the period: the policy number, the insured, the inception and expiry dates, the class of business, where the risk is located, the sum insured or limit and the premium. A premium bordereau sets out the money, either everything written in the period or only what has been paid, with tax, commission and the net amount due to the insurer. A claims bordereau lists each claim with its dates, the cause of loss, what has been paid and what is held in reserve. The table above shows the common fields for each type.
How often bordereaux are sent, and in what format, is set by the binding authority agreement rather than by law. Monthly is the usual rhythm, with the file due a set number of days after the month ends. For business written on Lloyd's paper, the fields follow the Lloyd's Coverholder Reporting Standards, so that every syndicate receives the same data in the same shape. Insurers outside Lloyd's set their own templates, which is why an MGA with several capacity providers can be producing several versions of the same report every month under its delegated authority arrangements.
How do MGAs and insurers produce and check bordereaux?
Many still build bordereaux in spreadsheets. Someone at the MGA or coverholder exports data from one or more systems, rekeys or reformats it into the insurer's template and emails it across. At the other end, an insurer, managing agent or outsourced team cleans the file, maps it into its own systems and goes back with queries when fields are missing or do not reconcile with the money received. Every manual step adds delay and a chance of error, and the insurer only sees the business weeks after it was written.
The alternative is to produce bordereaux from the system that already holds every policy, endorsement, payment and claim, so the report is an output of the data rather than a copy of it. Genasys generates and reconciles risk and paid bordereaux from the same platform that runs policy administration, claims and billing, so the figures in the report match the policies and payments behind them. Where an insurer can take data by API, the same records can reach it as they are written, which shortens the wait between a policy being bound and the insurer seeing it.
We'd rather show you than tell you.
We'll start by getting to know your business. Then we'll show you exactly how Genasys handles it.
Insurance People
Zero Fluff
Tailored to You